

A familiar claim in nature finance is that nature could become a trillion-dollar asset class. It typically starts with a striking statistic: more than half of global GDP depends moderately or highly on nature. The conclusion seems obvious – if nature underpins such vast economic value, financial markets should mobilize large-scale investment to protect it.
But this reasoning collapses three distinct concepts: economic value, financial cash flow, and investability. These are related but not interchangeable – and disentangling them is essential to understanding why nature finance often underdelivers.
Nature is extraordinarily valuable – both intrinsically and economically. That does not mean it produces investable cash flows. Until that financial translation problem is addressed, capital will struggle to engage – regardless of how instruments are structured.
The category error: value is not cash flow
Economic value reflects the broad benefits ecosystems provide to society. Financial cash flow – what markets actually finance – refers to revenue that can be captured and contracted. Investability requires that those cash flows are predictable, enforceable, and attributable to a specific asset.
Nature, however, primarily produces public goods and avoided losses rather than financial cash flows. For example:
Mangroves reduce storm surge
Coral reefs attenuate wave energy
Wetlands absorb floodwater
Ecosystems stabilize fisheries, water systems, and agricultural productivity
To be clear, nature does produce direct revenue in specific, mature sectors such as sustainable forestry and regenerative agriculture, where outputs are private commodities. The translation problem becomes acute when moving beyond these commodity-based activities to systemic services – such as flood mitigation or biodiversity protection – that function mainly as public goods.
These benefits are real and often substantial. In many cases, the economic value of ecosystem services is large relative to the cost of protection or restoration. It follows naturally that ecosystems are often described as “natural infrastructure.” But in financial terms, they are not infrastructure unless there is a payer, a contract, and a defined revenue stream.
The challenge, then, is not demonstrating that nature is valuable. It is establishing mechanisms through which that value is translated into enforceable payments.
The pipeline problem – or the revenue problem?
A common claim is that capital is available, but projects are missing. Institutional investors, the argument goes, are seeking natural capital exposure. The constraint is a lack of bankable pipeline.
There is some truth in this. Project preparation capacity is often limited, and many opportunities do not meet investor requirements – lacking sufficient scale, standardized structures, clear revenue models, or risk profiles that can be assessed and priced.
Aggregation is often presented as a way to address this – bundling smaller projects to meet investor scale requirements. But aggregation addresses scale, not the underlying revenue constraint. Without underlying cash flows, bundling projects simply produces a larger portfolio with the same limitation.
Systematic reviews highlight that financing barriers extend beyond project availability to include gaps in valuation, monetization, and coordination across actors. The pipeline framing is therefore incomplete: many projects exist, but far fewer meet the conditions required for capital to engage on commercial terms.
Blended finance and the limits of risk allocation
Blended finance is often presented as a solution. It combines public or philanthropic capital with private investment to improve risk profiles and attract commercial participation. These structures can be effective where underlying revenue streams exist but are not yet sufficient to meet investor requirements, such as in sustainable aquaculture or ecosystem-linked tourism.
In these contexts, concessional capital can absorb specific risks, extend tenors, or support early-stage project development, helping projects move from early-stage development into investable transactions, and enabling participation by a broader set of investors.
In many nature-related applications, however, the challenge is different. Ecosystem services often generate diffuse benefits or avoided losses rather than direct income streams. In other cases, such as small-scale fisheries or seaweed farming, revenues exist but may be insufficient, volatile, or difficult to structure in ways that meet investor requirements. In these cases, blended finance can support project development and financing, but it does not create new revenue streams – it works with those that already exist.
Blended finance, then, operates primarily by redistributing risk around an existing or partially viable economic activity. This does not diminish its catalytic role in enabling transactions – but it operates on existing or proximate revenue streams rather than creating them.
Outcome-based finance: introducing a payer
A different approach does not try to fix the revenue gap – it works around it by introducing a payer. Outcome-based or performance-linked structures link investor returns to measured environmental outcomes. In current designs, outcome payments are committed in advance – typically by public or philanthropic actors – and disbursed if predefined ecological outcomes are achieved.
These structures are often described as mobilizing private capital for nature or establishing nature as an investable asset class. In practice, the linkage is more indirect. Most investor capital remains on the issuer’s balance sheet for general purposes. A portion may be directed to conservation through the transaction structure or associated commitments, but this typically represents a small share of total proceeds. Recent examples, including the Rhino Bond and more recent Cape Water Performance-based Bond, follow this model.
Investors typically hold principal-protected exposure to a high-grade issuer, with potential upside linked to performance. In this configuration, investors provide capital to the issuer, while outcome funders provide the payments that drive performance-linked returns. These payments are embedded within the transaction structure and funded externally, rather than generated by the ecosystem itself. Investor exposure remains primarily to issuer credit, with ecological performance affecting returns rather than principal.
Investor participation is also often concentrated among a small number of large, development-oriented institutions. In the Cape Town Water Performance-based Bond, a single institution, the IFC, purchased 64% of the issuance, limiting the extent to which the transaction reflects broad-based capital markets participation.
These structures introduce a payer where one does not otherwise exist. They can play a useful role in channeling funding and improving outcome accountability. But they rely on continued public or philanthropic funding to operate, rather than establishing self-sustaining sources of revenue.
The energy transition analogy
The same constraint has appeared in other sectors. The energy transition provides a useful comparison.
As with nature, clean energy technologies are enormously valuable to the economy and the environment. But renewable energy did not scale simply because that value was recognized.
It scaled because governments created payment mechanisms that translated societal value into financial revenue: feed-in tariffs, power purchase agreements, tax credits, and subsidies. These instruments defined who pays, how much, and under what terms. They created predictable, contractible cash flows tied to electricity generation – revenues that could be modeled, financed, and securitized. Once those payment structures existed, private capital followed.
The lesson is not that nature should mimic energy markets directly. It is that investment scales only when value is translated into defined, contractible revenue through institutional design. Without that step, even assets of clear economic importance remain outside the scope of capital markets.
Nature and the financial translation problem
This distinction can be summarized more directly:
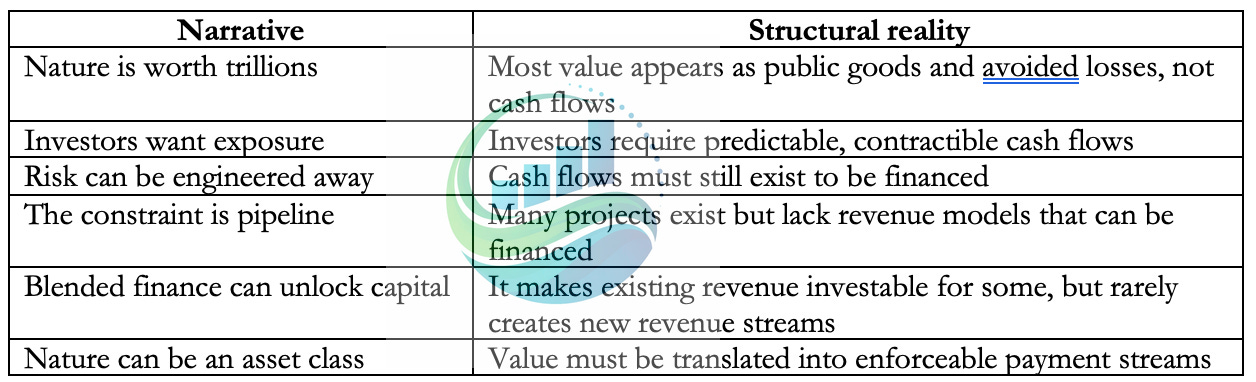
What makes nature investable
Nature becomes financeable only when ecosystem value is translated into enforceable payment streams through defined institutional mechanisms. In practice, four conditions must hold simultaneously:
a clearly defined payer (who pays),
a contractual payment mechanism (how payment is made),
a durable economic or institutional basis for payment grounded in revenues, avoided costs, risk reduction, regulatory obligations, public budgets, procurement mandates, or contracted demand, rather than created solely within the financial structure (what sustains the payment), and
credible measurement and verification systems to confirm that the ecological outcome being paid for has been delivered (what is being paid for).
Where these conditions are met, capital can engage. Examples are beginning to emerge:
In the UK, biodiversity net gain requirements create legally enforced demand for habitat restoration, generating revenue tied to measurable ecological outcomes.
In the United States, the U.S. Army Corps of Engineers’ Engineering With Nature initiative integrates ecosystem-based approaches into coastal infrastructure, embedding them within publicly funded investment programs.
Sovereign debt conversions, such as those in Ecuador and Belize, enable conservation funding by optimizing sovereign fiscal space.
In carbon markets linked to nature, including blue carbon, revenue can be generated where emissions reductions or removals are converted into tradable credits with defined buyers. These markets create a paying counterparty and a contractual payment mechanism, though demand is policy- or reputation-driven and prices remain variable.
In each case, capital flows not because nature inherently generates investable cash flows, but because institutions define who pays, and on what terms. That is the missing step.
Nature does not need to become an asset class to be financed. It needs payment systems that make its value legible to finance. These are ultimately questions of policy and institutional design – not financial engineering alone.
Ledger Notes – Additional Reading
Much of the current discourse on nature finance is shaped by a set of influential reports that emphasize value, scale, and opportunity. The following provide useful context for the narratives this piece seeks to clarify.
World Economic Forum (2020), Nature Risk Rising: Why the Crisis Engulfing Nature Matters for Business and the Economy
Estimates that more than half of global GDP is moderately or highly dependent on nature, framing ecosystem degradation as a systemic economic risk to businesses and financial systems.Why it matters
This report underpins much of the “nature is worth trillions” narrative. It is directionally correct on systemic importance, but illustrates the central gap this piece addresses: economic dependence does not translate into investable cash flows.United Nations Environment Programme (2026), State of Finance for Nature
Provides the latest global assessment of finance flows to nature, highlighting a persistent and widening gap between current investment levels and what is required to meet biodiversity and climate targets. The report also tracks harmful versus positive flows and calls for scaling both public and private finance.Why it matters
The report frames the challenge primarily as a financing gap and emphasizes mobilizing capital at scale. This Substack piece suggests a complementary diagnosis: the constraint is not only the volume of capital, but the absence of payment mechanisms that translate ecosystem value into revenue streams that capital markets can finance.World Economic Forum (2026), 50 Investible Opportunities for a New Nature Economy
Identifies a wide range of “investible” opportunities across sectors such as regenerative agriculture, ecosystem restoration, and blue economy activities, with estimated multi-trillion-dollar economic potential.Why it matters
This work illustrates how economic value, cost savings, and avoided losses are often grouped together as “investible opportunities.” The distinction drawn in this piece is that only a subset of these opportunities generate contractible cash flows – highlighting the gap between opportunity framing and financial investability.
Sarah, good stuff!
This cuts through a lot of the fog in nature finance. The disaggregation of value, cash flow, and investability is exactly right — and the energy transition analogy reframes the whole conversation away from “where’s the capital?” toward “what institutional architecture is still missing?” which is sorely needed!
It maps closely onto a parallel problem I’ve been working on in refugee investing. Through the Refugee Investment Network, we developed a Refugee Lens — a taxonomy covering refugee-led enterprises, businesses that employ or serve refugees, economic integration, and social infrastructure. The common thread: enormous real-world value that capital can’t engage with because the financial translation layer doesn’t exist. No defined payers, no contractible structures, no credible verification.
Your four conditions are almost identical to what we kept running into. The value isn’t the problem. The scaffolding is.
I’ve been thinking about adapting the framework for nature — a Nature Investment Lens that screens opportunities by how many of your four conditions are already present, to distinguish what’s investable now from what needs policy intervention first. Would love to compare notes sometime.
Thanks, Sarah, for stating eloquently what should be obvious but is too often missed by the narrative: that most of nature’s value generation is public goods and avoided losses, not private goods with predictable bankable cash flows.